The network is built.
Now we franchise it.
121 coffee machines in the UAE across two directions: Subscription and Retail. We are finishing the supply base and the software, then taking the model to the franchise market. Raising AED 5M for 44% of the holding.
One holding. Four companies.
A working network in two formats. A supply base and software being completed on this round. Then an exclusive franchise offer and exponential growth.
Network
121 machines on the books, 116 running: 63 on Subscription in offices, 53 in Retail. Dubai, Abu Dhabi, Sharjah.
Roastery
A 15 kg O Tesla roaster, already paid for. Capacity 12 tonnes a month, and the coffee behind our capsule plans.
IT platform
Fleet control, POS, loyalty and the AI layer. IP assigned to the group.
Flagship cafe
200 m² in Dubai with the roaster behind glass. The shop window for franchisees.
An ADGM holding under English law. The holding owns at least 51% of each company. Rights are set by contract, not by custom.
AED 5M for 44%.
AED 1,136 per share. Cap table 5,100 founders / 4,400 investor / 500 option pool.
Released against milestones. Shares issue against money actually paid.
Full investor rights apply from the first payment, not from the last.
Founders contribute AED 1,105,000 in cash alongside the round, plus the existing network and the roaster. Counted at replacement cost, those assets are AED 1,851,812.
It held through the shock.
The 2026 downturn was our hardest quarter. The subscription channel recovered fastest and grew from 54 to 63 machines; it billed AED 68,105 in August 2026 and AED 465,578 across 2025. Average ticket in Retail is AED 10.7.
The two channels behave differently on purpose. Subscription is roughly 60% of network revenue and is predictable, and it has grown in every quarter since launch; Retail is seasonal and is moving to the micromarket format, where the same rent and the same operator visit produce more revenue per site.
Read: is a vending machine business in the UAE profitable? Real numbers from our network →
Actual monthly revenue, AED. Subscription line: January 2025 – August 2026 from our installation schedule, the same record the investor pack is built on. Retail line: January 2025 – June 2026 from Nayax terminal data. September 2026 is not shown because the month is still running.
Our clients & locations.
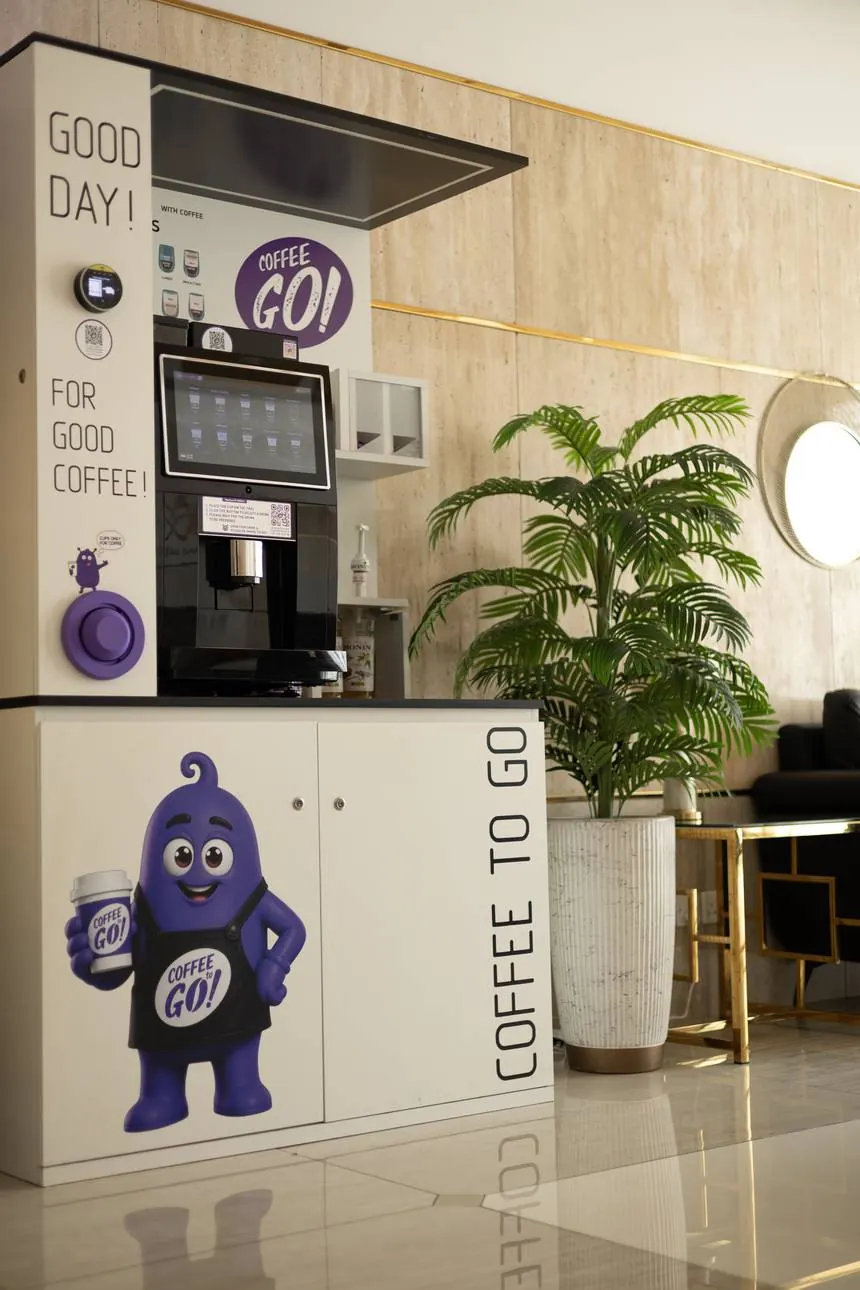
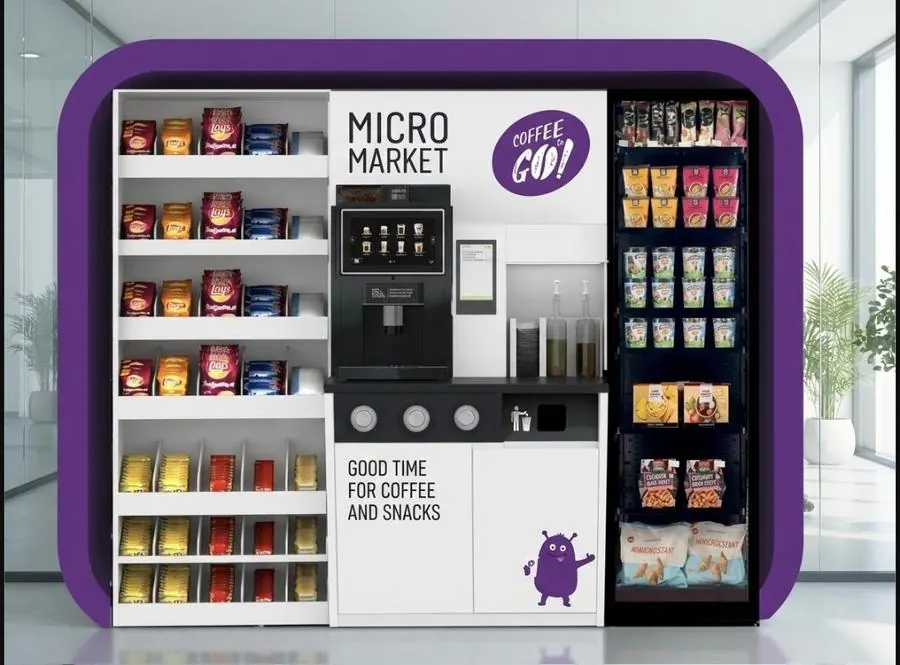
The micromarket.
Coffee, snacks and chilled food in one branded unit, placed free of charge. Same rent, same operator route, more revenue per location than a plain machine.
Two directions today. Three after October.
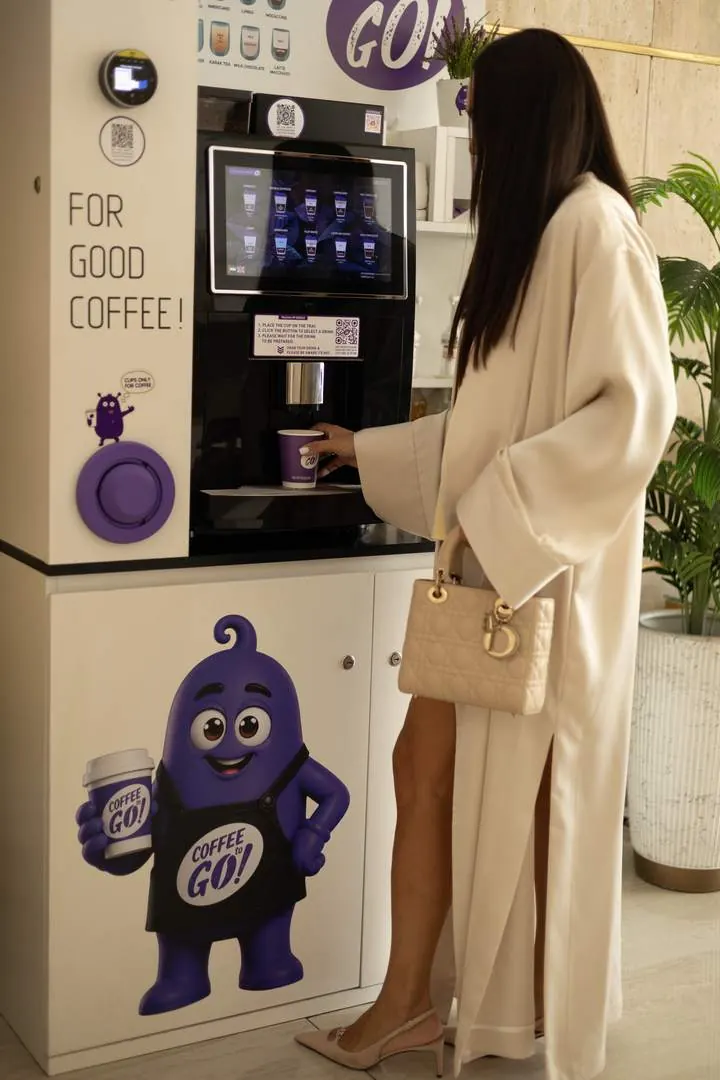
Offices on contract. The machine, installation and service are free; the client pays for ingredients monthly. About 60% of network revenue and the predictable part of it.
Self-service points in lobbies, buildings and malls. Our revenue, card payment through a Nayax terminal, rent paid to the host. Seasonal, and shifting to the micromarket format.
12 tonnes a month of capacity. Supplies the network, wholesale buyers, capsule subscriptions and, later, the franchise system.
The roastery has demand before it opens.
| Offtake secured before launch | kg / month | Share of capacity |
|---|---|---|
| Our own network consumption | 500 | 4% |
| Buyers with terms discussed, contracts not yet signed | 2,000 | 17% |
| Total before opening | 2,500 | 21% |
| Roaster capacity | 12,000 | 100% |
The working target for reaching full load is four months. The financial model assumes six, and every figure on this page is calculated on the six-month assumption. By year 5 the roastery runs at around 90 tonnes a month, almost all of it inside the franchise system apart from the specialty segment.
The roastery also opens a smaller subscription.
Today a subscription starts at AED 600 a month for a small team and AED 1,000 for a typical office — the size of the site has to justify a full bean-to-cup machine. Capsule machines remove that floor. Same contract logic, same delivery route, same coffee from our own roastery, but a site of three people becomes worth serving. It is the same offer extended downwards, not a new business.
| Capsule plan, per month | Capsules | CoffeeGo Blend | Oracle specialty |
|---|---|---|---|
| 3 packs | 30 | AED 69 | AED 89 |
| 4 packs — recommended | 40 | AED 89 | AED 115 |
| 5 packs | 50 | AED 109 | AED 135 |
| 6 packs | 60 | AED 119 | AED 155 |
| Full machine subscription, for comparison | — | AED 600 – 1,000+ | |
Planned tariffs, launching alongside the roastery. Paying a year up front takes 10% off and locks the plan for twelve months. The capsule machine itself is placed free, as the bean-to-cup machines are. These plans sit outside the base financial model — the model is built without them, so they are upside rather than an assumption.
Without the software it is just hardware.
The platform already runs the network: fleet telemetry, stock and route planning, POS and loyalty. This round funds the full launch of the AI layer.
Location choice is governed by a written policy: a 100-point score with a pass mark of 70, and a decision on any new site taken on contribution from the third full month, not on a hunch. Across sites with three or more active months, median revenue is AED 764 a month, the top quartile is above AED 1,144, and the best locations run AED 1,500–2,100.
Own sites fund it. Franchise scales it.
Own locations prove the unit and feed the roastery. Franchisees multiply it, and every one of them pays for the platform.
| End of project year | 1 | 2 | 3 | 4 | 5 |
|---|---|---|---|---|---|
| Own locations | 180 | 300 | 500 | 750 | 1,000 |
| Franchise locations | — | — | 732 | 2,904 | 6,000 |
| Total locations | 180 | 300 | 1,232 | 3,654 | 7,000 |
Starting point is 121 locations today. The IT subscription is AED 150 per location per month and the model reaches up to 8,100 locations on it. Year 1 means the first twelve months after the investment, not a calendar year.
Profitable from year two.
| Project year | 1 | 2 | 3 | 4 | 5 |
|---|---|---|---|---|---|
| Revenue, AED m | 12.0 | 39.5 | 91.7 | 150.2 | 208.1 |
| Net profit, AED m | −0.39 | 1.73 | 8.64 | 18.87 | 31.36 |
On revenue of AED 208.1M.
A line of AED 1.75M, peak drawdown in month 22, fully repaid by month 35.
The balance stays above AED 300,000 in all sixty months of the model.
Year 1 is loss-making by design: the roastery and the flagship cafe are built in it. Figures are from financial model v13, September 2026. They are a forecast, not a promise, and the full model with all assumptions is in the pack.
Cash, a way out, and the stake.
Policy of up to 30% of net profit, paid from year 4. On the model a 44% holder receives AED 1,140,414 in year 4 and AED 2,491,300 in year 5 — 73% of the investment back within five years, and 155% by year 6.
From month 36 the investor may require a buy-back once, at the Minimum Price in the shareholders agreement. On the modelled tranche dates that floor is about AED 6.77M, or 1.35× the money in, payable in instalments over up to 12 months.
Company value at year 5 by the formula written into the agreement, five times EBITDA. A private M&A range at 7–10× would be AED 304–434M. Anything above that needs a strategic buyer.
All three figures come from financial model v13 and the signed-form shareholders agreement. They are modelled outcomes, not guaranteed returns.
Released against milestones.
Production premises with a year of rent paid up front, fit-out, and working capital to launch the roaster.
A 200 m² site in Dubai with the roaster behind glass, plus the network and platform rollout.
AED 5,000,000 in total, from AED 1,000,000 down to AED 200,000, each against a milestone. Security by LC, guarantee or escrow is available if you want it.
Timing runs from the investment, not from a calendar. Month 1 is the month the first tranche is paid.
Structured to protect you.
The questions we get.
116 machines running.
Let's talk.
The full pack: proposal, 2-page summary, 14-slide pitch, financial model, valuation frame, shareholders agreement, term sheet and thirty due-diligence answers. English and Russian. We reply within one business day.
Leo Stark, Founder and CEO — poleonid@coffee-go.com · +971 55 242 1171
Nikita Bugaevskii — bugaevskii@coffee-go.com · +971 58 532 9288
© 2026 CoffeeGo (COFFEEGO FOR SELLING PRODUCTS & SERVICES BY AUTOMATIC VENDING MACHINES CO. L.L.C, Jebel Ali, Dubai). This page is informational only. It is not an offer of securities, an invitation to invest or investment advice, and it is not directed at any person in a jurisdiction where such an offer would be unlawful. Forward-looking figures come from financial model v13 of September 2026 and are projections, not guarantees; actual results will differ. Trading figures reflect the September 2026 investor pack and a normalised trading month. The shares described would be issued by a holding company to be incorporated in ADGM.